Geoficiency: Accounting Risk Detection and Reduction Software
With our end-to-end accounting control and investigation solution, strengthen compliance and the robustness of your analysis. Investigate in depth: on a complete, harmonised dataset, your controls become more precise and your analysis more strategic.
Be audit-ready. Transform finance faster.
The Only Risk Detection Solution that Unifies and Analyses 100% of your Accounting Entries
On a harmonised, complete dataset, your controls gain precision, your analysis gains reach, and you can prove the effectiveness of your control framework.
And because a model is only as good as the data behind it, that trusted data foundation also becomes the base on which to run your own AI use cases, rather than starting again from one-off extracts.
Smoother Controls, Sharper Decisions.
-
Harmonise 100% of your accounting data

-
Detect fraud and error risks
-
Prove the effectiveness of your controls
-
Simplify compliance
-
Improve efficiency and collaboration
-
Keep your accounting activity under control
Get Harmonised Accounting Data, Ready for Analysis
Effective controls start with complete, comparable data. Geoficiency centralises and unifies your heterogeneous data into a single, usable dataset:
- Bring together data from all your ERPs, whatever the chart of accounts, currency, or language
- Each chart of accounts is mapped to a common group framework, so your entries become comparable from one entity to the next
- Work from a complete, harmonised dataset containing 100% of your entries
- Put an end to manual rework that undermines confidence in the figures and eats into analysis time
Detect Fraud and Error Risks in your Accounting
Take control of the quality of your accounting entries and build comprehensive, consistent indicators:
- Draw on a library of modular controls, built-in or custom, enhanced by AI
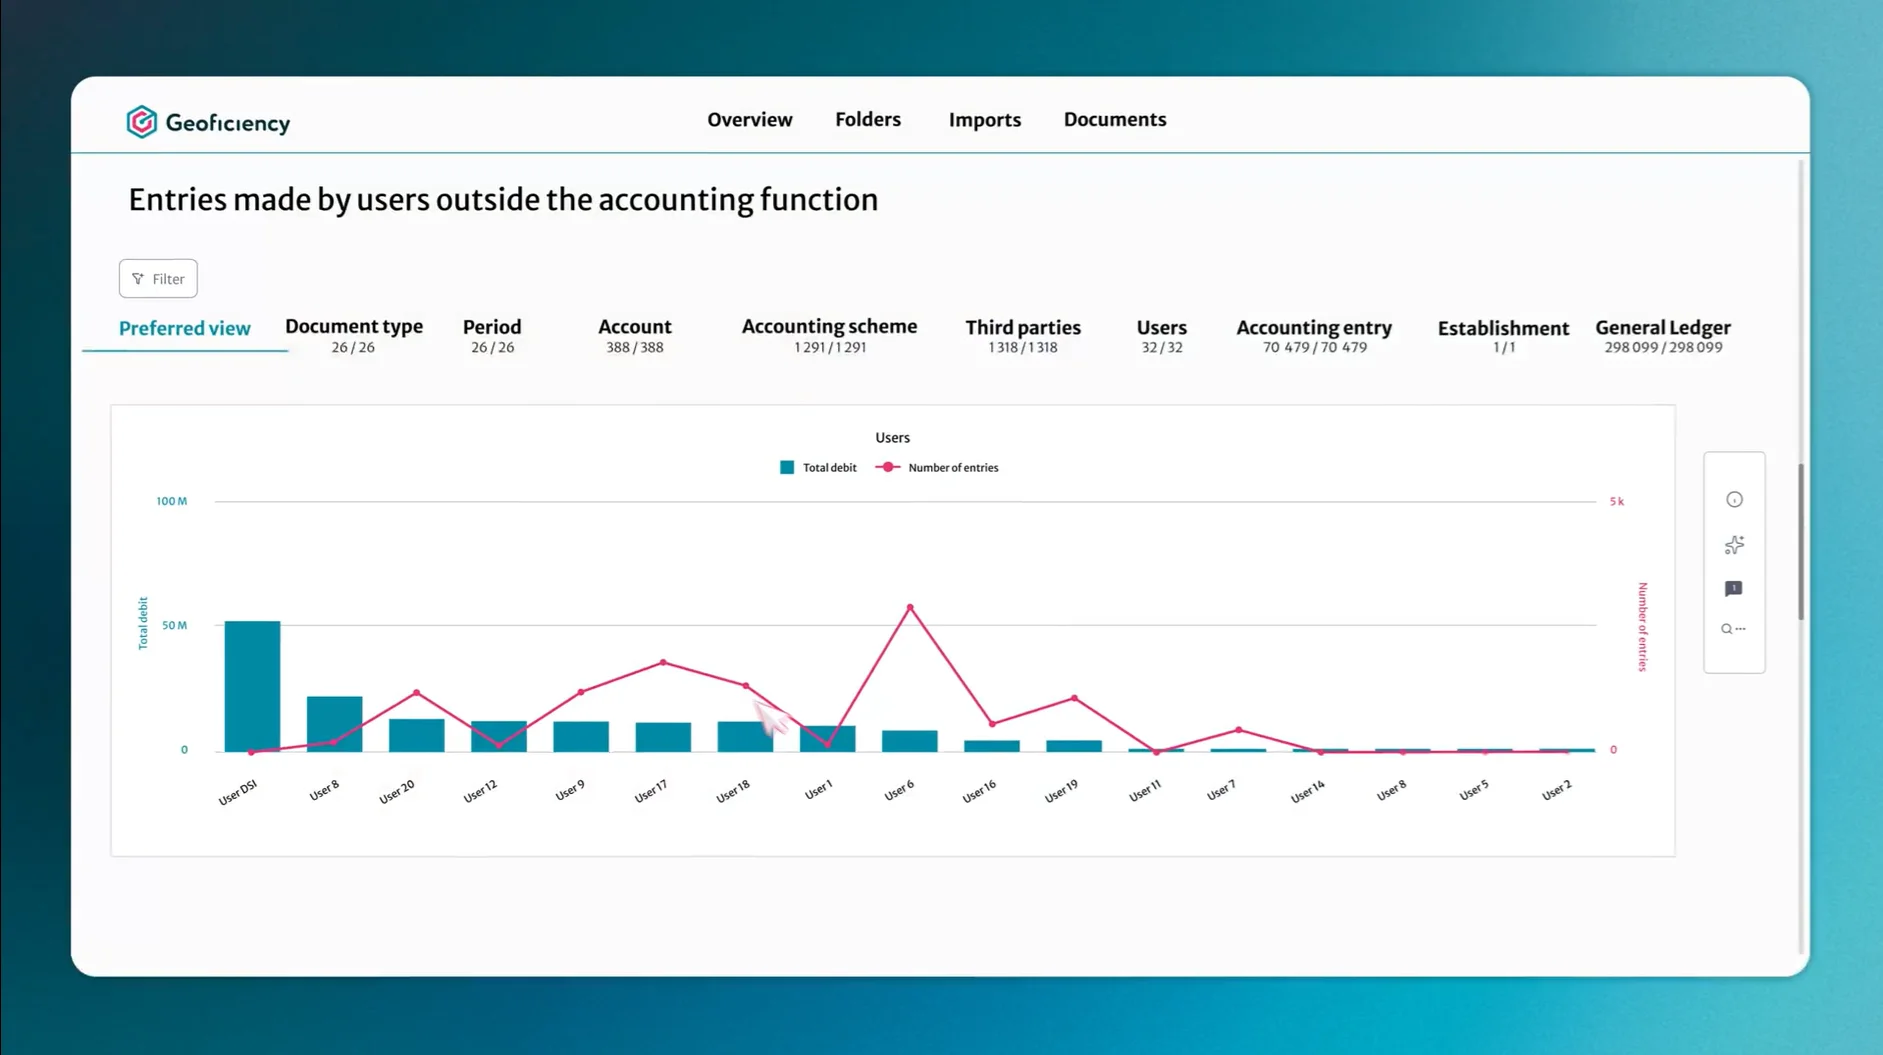
- Use automatic alerts and pinpoint anomalies with entry profiling
- Identify risk areas precisely (transactions, entries, entities) and focus your efforts where it matters
- Track your risk indicators consistently across your entire scope
- Built for complex multi-ERP, multi-entity environments: Geoficiency cross-analyses results across entities to surface what a siloed review would miss.
Prove the Effectiveness of your Controls at Any Time
Evidence that controls have been performed gets scattered across emails, local files, and informal notes. Geoficiency structures that evidence as each control is performed:
- Document and trace every control and its conclusion as it is performed, not after the fact
- Build a defensible audit trail: who checked what, when, and on which data
- Base your controls on complete data rather than samples
- Save considerable time with external auditors and regulators, without reconstructing evidence retrospectively

Simplify Compliance
Respond effectively to regulatory requirements (anti-corruption and anti-fraud laws such as ECCTA, supplier payment terms, tax requirements, etc.) with clear, documented oversight:
- Activate all the first-, second-, and third-level anti-corruption accounting controls to perform and document
- Link your controls to your corruption risk assessment
- Step up your fight against fraud with automated, targeted accounting controls
- Monitor compliance with supplier payment terms and reduce the risk of late-payment penalties through automated tracking of overdue payments
- Automatically trace your controls and conclusions, with documentation and archiving included
- Stay up to date with regulatory changes through regular product updates
Improve Process Efficiency and Team Collaboration
Streamline work between finance, accounting, audit, compliance, and internal control on a single platform:
- Continuously improve your processes and their accounting footprint to put an end to hidden performance losses
- Reduce errors and post-close adjustments with better-controlled processes
- Collaborate on a single shared platform for greater clarity, while respecting segregation of duties
- Automate repetitive tasks to free up time for high-value work
- Manage your control campaigns with clear, dynamic dashboards
Keep your Accounting Activity Under Control
Identify your risk areas effortlessly and base your decisions on data-driven diagnostics:
- Detect risks and trigger alerts for a targeted, agile response
- Run more efficient internal audits and streamline interactions with external auditors
- Strengthen your M&A and post-acquisition due diligence: access consistent indicators, quickly spot red flags, and support your decisions with an additional rapid diagnostic
A platform for control and analysis created alongside our clients, to transform and accelerate.
Solutions designed with our users for our users
Strategic guidance supported by subject matter experts
A robust, fast, and secure platform designed to meet the pace of your challenges

Immediate adoption. Efficiency from the very first click.
A solution that adjusts to your reality, not the other way around.
We needed an agile tool that could allow us to meet our organisational needs. Given that we operate multiple ERPs deployed worldwide, use different chart of accounts, and manage multi currency accounting.
The benefits: time savings, ease of deployment, standardisation of processes and methodologies

Now, I can't envisage working without Geoficiency
Designed for Seamless Integration.
A clear, intuitive platform custom-made for your organisation, stakeholders, and priorities.
Your Frequently Asked Questions about
Accounting Control and Analysis
1. How can anomalies be quickly identified in a growing volume of accounting entries?
When transactions reach a certain volume, weak signals more easily slip under the radar. The challenge is to move from a sampling approach (which does not allow weak signals to be detected) to a comprehensive analysis of flows, with alerts calibrated to the organisation’s actual risks. Thanks to this comprehensiveness and targeting, automation produces relevance, and teams can focus on the real issues without being overwhelmed by ineffective sample analyses or false positives.
2. How to guarantee data quality, comprehensiveness and consistency across multiple ERPs and subsidiaries?
The heterogeneity of source systems is often considered the main obstacle to reliable and effective analysis: a disparate chart of accounts, different data formats, currencies and languages, multiple technical or business contacts.
The reliability of analyses therefore depends on a preliminary stage of data harmonisation and standardisation, regardless of the heterogeneity of the sources, which is therefore essential. Without this standardised “source of truth,” manual reprocessing will accumulate, and confidence in your consolidated figures will remain fragile.
3. How can accounting controls be made more objective and reliable in order to avoid comments from statutory auditors or the Board?
Audit comments rarely flag gross errors: they most often target insufficient justifications, unexplained discrepancies or controls whose actual execution cannot be proven. Objectifying controls means relying on comprehensive data rather than sampling and producing documented and traceable conclusions for each control point. It’s the shift from a system that reassures by its form to one that convinces by its substance through comprehensive data and traceable conclusions.
4. How can you prove that controls are properly performed, documented and traceable?
Traceability is often the missing link in internal control systems: controls are performed, but evidence of their execution is usually scattered across emails, local files and informal notes making audit reconstruction a nightmare. In the event of an AFA or statutory audit, a coherent audit trail is available instantly, protecting the organisation from doubts about its control effectiveness. Easily structuring documentation at the time of execution, rather than after the fact, is the only viable approach at the group level.
5. How to prevent the risk of internal fraud linked to manual journal entries?
Various manual operations remain the most common vector for accounting manipulation: lack of validation workflow, vague descriptions, unusual users, batch bypassing, unusual posting hours. These isolated signals are invisible in a traditional review but revealing when you have the ability to analyse the entire flow with profiling entry behaviour. This isn’t about suspecting your team; it’s about building a system robust enough to deter and detect any attempt at fraud automatically.